Baloney Inspection Report: Claim #1173 · Inspected Oct 31, 2026, 7:48 AM PDT · Scoring model v2
 35%
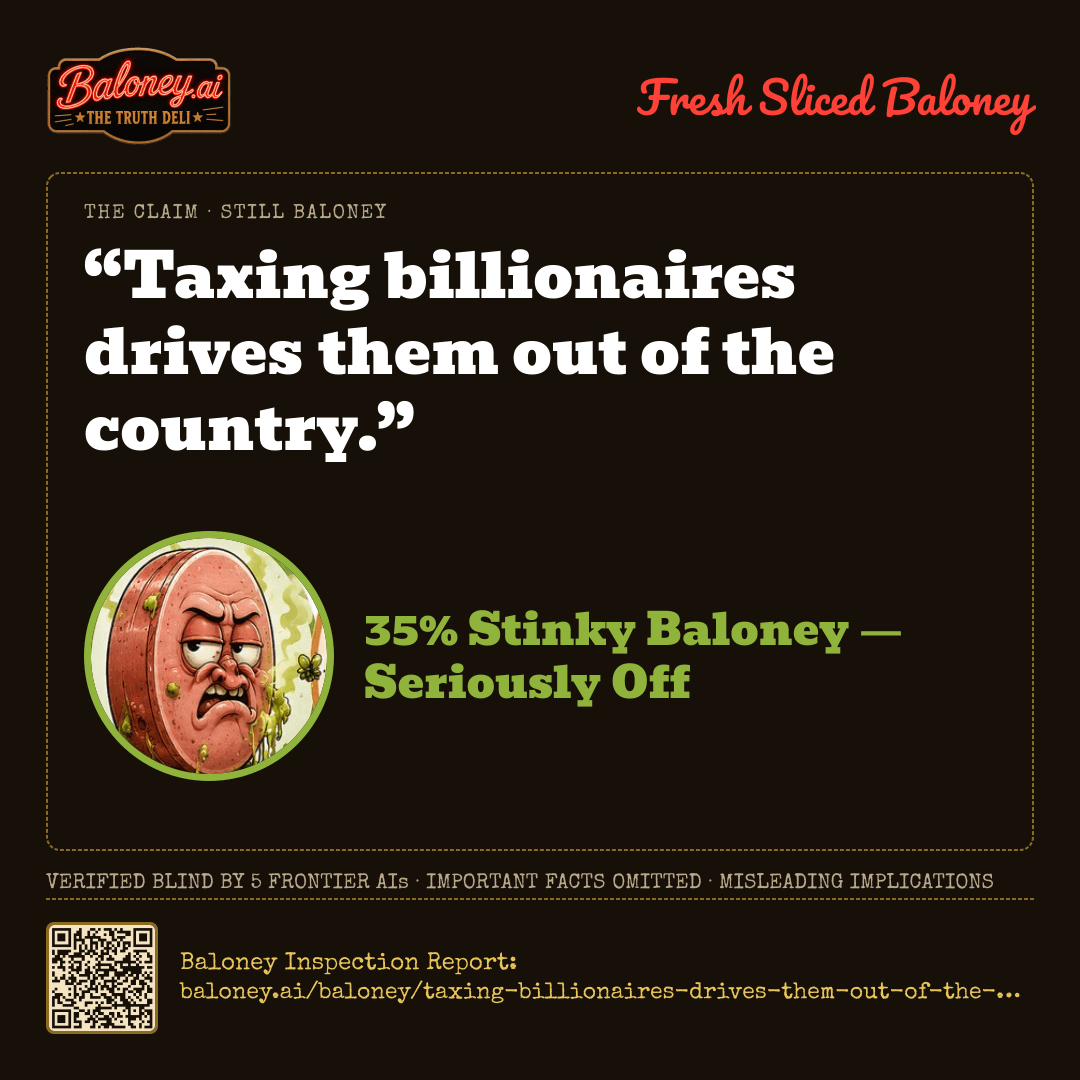
“Taxing billionaires drives them out of the country.”
35%Stinky Baloney — Seriously Off
That’s not the whole story…
Important facts omittedMisleading implicationsCherry-picked infoSpins the truth
Serve It Fresh
Ready to Serve19 servings
Serve it the way you want it
The Verdict
 “Taxing billionaires drives them out of the country.”35% Stinky Baloney — Seriously OffVerified blind by 5 frontier AIs · Baloney Inspection Report: baloney.ai/baloney/taxing-billionaires-drives-them-out-of-the-country
The Baloney Sampler
The claim treats a real, limited pattern as a general rule. Some wealthy people do relocate after tax increases, especially in small open economies with free movement. The Journal of Economic Perspectives finds mobility responses that are significant for narrow groups such as foreign high earners, and the Quarterly Journal of Economics documents that Denmark's preferential scheme for foreign top earners changed location choices. The Guardian reported wealthy Norwegians leaving after a wealth-tax rise. That is not wholesale flight of billionaires.
The American Sociological Review, using U.S. tax records, found millionaire migration lower than the general population's and only marginally driven by taxes, because the rich are embedded by family, firms, and social ties. The Internal Revenue Service taxes U.S. citizens worldwide and levies an expatriation tax on unrealized gains, so leaving the country does not end U.S. tax. The EU Tax Observatory finds revenue from taxing the very wealthy exceeds losses from the few who leave.
Resting on Internal Revenue Service · Journal of Economic Perspectives · Quarterly Journal of Economics · American Sociological Review
Original Claim Source https://www.washingtonpost.com/opinions/2026/10/12/britain-billionaire-exodus-is-warning-california/
Other ways to slice it — phrasings that might have changed the rating
- “Some wealthy residents of small open economies relocate after wealth-tax increases.” The reports document Norwegian and French departures and tax-sensitive moves where migration barriers are low, which is the limited mechanism the blanket claim inflates.
- “Billionaires do not leave a country because of taxes.” Research on foreign top earners, inventors, and Norwegian wealth-tax payers shows some tax-motivated relocation, so denying any response would ignore that documented kernel of truth.
- “Taxing billionaires fails to raise revenue because they leave the country.” The EU Tax Observatory and related studies find that revenue from those who stay exceeds losses from the few who emigrate, which is the policy conclusion the original claim implies but does not establish.
Written from the panel’s reports by xAI · grok-4.6. Nothing here changed the score.
The Order Ticket
14:48:49CLAIM RECEIVED — QUEUED FOR INSPECTION✓
14:50:01claude-opus-5 REPORTED — SCORE 36, CONFIDENCE 78✓
14:49:20gpt-5.5 REPORTED — SCORE 35, CONFIDENCE 82✓
14:49:23gemini-3.1-pro-preview REPORTED — SCORE 45, CONFIDENCE 95✓
14:48:54sonar-pro REPORTED — SCORE 32, CONFIDENCE 82✓
14:50:53grok-4.6 REPORTED — SCORE 26, CONFIDENCE 68✓
14:53:45PRIMARY MASTER GROK — SCORE 35✓
14:51:05BLIND VALIDATION GEMINI — SCORE 35✓
14:55:10AGREEMENT CONFIRMED — DELTA 0✓
14:55:10SCORING MODEL V2 — MEDIAN OF 5 COUNTED LAB SCORES: 36, 35, 45, 32, 26 → 35.✓
14:55:10SOURCE RULE — LABS CITED 26 SOURCES: 0 DISCARDED FOR HAVING NO URL, 1 DISCARDED AS DEAD LINKS (404/410), 12 COULD NOT BE OPENED BY US AND ARE MARKED UNVERIFIED.✓
14:55:10SOURCE RULE — PRIMARY MASTER RULED ON 19 SOURCES: 0 DISCARDED FOR HAVING NO URL, 0 DISCARDED AS DEAD LINKS, 9 MARKED UNVERIFIED, 10 VERIFIED.✓
How This One Was Sliced
Station 1 · Blind Inspection — Five Graders, Zero Peeking
Each lab scored the claim independently, without seeing the others. Open a breakdown for its evidence, its sources, and how sure it was.
Anthropic · EQUAL WEIGHT · 72.1s
claude-opus-5
36%BALONEY
ROUND-1 BREAKDOWN
Evidence offered for the claim- Norway's 2022 increase in wealth tax (to ~1.1%) was followed by a record number of wealthy residents relocating, mostly to Switzerland. Norwegian reporting (Dagens Næringsliv, relayed internationally) counted roughly 30 billionaires/multimillionaires leaving in 2022 — more than in the previous 13 years combined — including the country's richest man, Kjell Inge Røkke.
- France's wealth tax (ISF, 1989–2017) was associated with a documented stream of 'exil fiscal' departures of high-net-worth individuals, and the tax was ultimately narrowed to real estate in 2018 partly on competitiveness and capital-flight grounds.
- Peer-reviewed research confirms that top earners and the very wealthy are genuinely tax-sensitive in their location choices at the international margin. Kleven, Landais, Saez and Schultz (QJE 2014) found Denmark's preferential tax scheme for high-earning foreigners doubled the inflow of such workers — an elasticity near 1.5–2 for foreign top earners.
- Akcigit, Baslandze and Stantcheva (AER 2016) found top-quality inventors' international location decisions respond significantly to top tax rates, especially for foreign-born inventors (elasticities around 1).
- Moretti and Wilson (AER 2017) found star scientists' cross-state location in the US responds measurably to state income and business taxes, showing mobility responses are real where moving costs are low.
- Kleven, Landais, Muñoz and Stantcheva (JEP 2020) conclude that mobility responses of the highest earners to taxation are 'significant' in settings with low migration barriers (e.g., within the EU) and should be factored into optimal tax design.
- Spain's regional wealth tax variation (Madrid's 100% rebate) produced documented relocation of wealthy taxpayers to Madrid, showing within-country flight where the tax differential is large and moving costs are trivial.
- Anticipating this, several governments (Switzerland's lump-sum regimes, Italy's €100k/€200k flat tax for new residents, Greece, Portugal's former NHR, UAE) actively market tax residency to the ultra-wealthy, and such schemes do attract movers.
Evidence against the claim- The claim is stated as a general rule, but the measured magnitudes are small: in the largest administrative-data study of US millionaires (Young, Varner, Lurie and Prisinzano, American Sociological Review 2016, 45 million tax records), millionaire migration was *lower* than that of the general population — about 2.4% move across state lines annually versus 2.9% — and the share of moves attributable to tax differentials was tiny.
- Advani, Burgherr and Summers' UK work on the 2017 non-dom reform found that only a small minority (on the order of 0.2% of affected individuals per percentage-point of tax) emigrated; the overwhelming majority of those hit by a large tax increase stayed, and the reform still raised substantial net revenue.
- Norway's own numbers are far smaller than the headlines suggest in proportional terms: the departures involved dozens of individuals out of tens of thousands of wealth-tax payers, and Norwegian government and academic analysis disputes that net revenue fell; the wealth tax continued to raise billions of kroner, and some departures were driven by dividend-tax changes rather than the wealth tax alone.
- France's ISF: official French estimates put annual departures at roughly 500–900 taxpayers out of ~350,000 ISF filers (well under 0.5%), and the tax's revenue problems were driven more by exemptions, valuation caps and avoidance than by emigration.
- Billionaires in particular face very high exit costs: business operations, family, citizenship-based taxation (the US taxes citizens worldwide and imposes an exit tax under IRC §877A), social and political networks. Research consistently finds the super-rich are 'embedded' rather than footloose.
- Most country-level evidence of 'flight' comes from small open economies with free movement (Norway, within-EU, within-US-states). For a large economy with citizenship-based taxation and expatriation taxes like the United States, there is no evidence of billionaire exodus following tax increases.
- Much of the 'exodus' reporting is based on wealth-migration estimates from commercial firms (e.g., Henley & Partners/New World Wealth), which are modelled from LinkedIn and media scraping, not official registry data, and have been criticised as unverifiable marketing material.
- Evidence of flight does not establish net revenue loss: the relevant question is whether departures offset revenue gains. Multiple studies (Advani et al.; EU Tax Observatory) find the revenue from taxing the very wealthy substantially exceeds the losses from the small number who leave, which is why the claim's implied policy conclusion does not follow.
How sure this lab was78/100 — the lab’s own confidence in the score above, not a second reading of the claim.
SourcesThe Guardiannews · 82 · Journal of Economic Perspectives (American Economic Association) — Kleven, Landais, Muñoz & Stantcheva, 'Taxation and Migration: Evidence and Policy Implications'journal · 96 · Quarterly Journal of Economics — Kleven, Landais, Saez & Schultz, 'Migration and Wage Effects of Taxing Top Earners: Evidence from the Foreigners' Tax Scheme in Denmark'journal · 95 · American Economic Review — Akcigit, Baslandze & Stantcheva, 'Taxation and the International Mobility of Inventors'journal · 94 · American Economic Review — Moretti & Wilson, 'The Effect of State Taxes on the Geographical Location of Top Earners: Evidence from Star Scientists'journal · 94 · American Sociological Review — Young, Varner, Lurie & Prisinzano, 'Millionaire Migration and Taxation of the Elite'journal · 92 · Center on Budget and Policy Priorities, 'Tax Flight Is a Myth'other · 68 · EU Tax Observatory, Global Tax Evasion Report 2024other · 80 · U.S. Internal Revenue Service — Expatriation Tax (IRC §877A)gov · 97
OpenAI · EQUAL WEIGHT · 31.1s
gpt-5.5
35%BALONEY
ROUND-1 BREAKDOWN
Evidence offered for the claim- There is credible evidence that some very wealthy people relocate in response to wealth or top-income-tax changes. A prominent recent example is Norway: after a modest increase in its wealth tax, The Guardian reported that a record number of super-rich Norwegians moved abroad, many to Switzerland, including billionaire Kjell Inge Røkke.
- Economic research supports the mechanism that taxes can influence migration for highly mobile high-income groups. Kleven, Landais, Saez and Schultz found that preferential tax treatment in Denmark affected the location choices of high-earning foreigners, showing that tax-motivated migration is real in some settings.
- The OECD’s review of net wealth taxes says mobility, avoidance, valuation problems, and administrative challenges are among the reasons countries worry about or have repealed wealth taxes, so policymakers are not inventing the concern from nothing.
Evidence against the claim- The claim is too broad as written. The strongest evidence supports 'some rich people may move under some tax regimes,' not that taxing billionaires generally 'drives them out of the country.'
- Peer-reviewed evidence on U.S. millionaires found that millionaire migration is generally low and that tax-induced migration is small; Young, Varner, Lurie and Prisinzano concluded that the rich are often socially and economically embedded where they live, limiting tax flight.
- A broad review in the Journal of Economic Perspectives found that migration responses to taxes vary greatly: they can be large for narrow groups such as foreign professionals, athletes, or retirees, but are much smaller for the general population of top earners and natives. That undercuts a blanket claim about billionaires as a class.
- Even the Norway example shows partial movement, not wholesale flight. It is evidence that tax design can cause some departures, but not that billionaire taxation inevitably empties a country of billionaires.
How sure this lab was82/100 — the lab’s own confidence in the score above, not a second reading of the claim.
SourcesThe Guardiannews · 82 · OECDgov · 92 · Journal of Economic Perspectives / American Economic Associationjournal · 95 · Quarterly Journal of Economicsjournal · 95 · American Sociological Reviewjournal · 94
Google · EQUAL WEIGHT · 34.1s
gemini-3.1-pro-preview
45%BALONEY
ROUND-1 BREAKDOWN
Evidence offered for the claim- Historically, some nations with residence-based taxation have experienced measurable capital flight after enacting steep wealth taxes. For example, France's solidarity tax on wealth (ISF) led to the emigration of thousands of millionaires and billionaires to neighboring lower-tax countries like Belgium and Switzerland, eventually contributing to the tax's repeal in 2017.
- There are prominent anecdotal examples of wealthy individuals changing their citizenship or residence specifically to reduce their tax burden. A widely cited example is Facebook co-founder Eduardo Saverin, who renounced his U.S. citizenship and moved to Singapore shortly before the company's IPO, avoiding significant capital gains taxes.
- Economic models of tax competition suggest that highly mobile, high-net-worth individuals are sensitive to marginal tax rates, particularly in regions like the European Union where cross-border relocation is legally seamless.
Evidence against the claim- Extensive sociological and economic research, such as studies utilizing decades of administrative tax data, demonstrates that 'tax flight' among the ultra-wealthy is largely a myth. Billionaires are heavily 'embedded' in their home countries through business networks, family ties, and cultural connections, making their actual rate of transnational migration exceptionally low.
- The claim ignores how different tax systems function, particularly in the United States. The U.S. employs a citizenship-based taxation system, meaning American billionaires are taxed on their worldwide income regardless of where they live. Simply moving out of the country does not relieve them of U.S. tax obligations.
- To fully escape U.S. taxes, an American billionaire must formally renounce their citizenship. Doing so triggers a massive 'Exit Tax' (Expatriation Tax) under IRC Section 877A, which taxes all unrealized capital gains on their worldwide assets as if they were sold on the day before expatriation, making tax flight financially punitive.
- Empirical data consistently shows that the migration rate of millionaires and billionaires is actually lower than that of the general population, and the relocations that do occur are predominantly driven by non-tax factors like family, climate, and local business opportunities.
How sure this lab was95/100 — the lab’s own confidence in the score above, not a second reading of the claim.
SourcesAmerican Sociological Reviewjournal · 95 · Internal Revenue Servicegov · 100 · NPRnews · 90 · Center on Budget and Policy Prioritiesother · 85
Perplexity · EQUAL WEIGHT · 4.6s
sonar-pro
32%BALONEY
ROUND-1 BREAKDOWN
Evidence offered for the claim- Some wealthy people do relocate in response to tax incentives. A large administrative-data study of 3.9 million top earners found that tax incentives affect migration at the margin, although social and professional ties substantially limit mobility.[1]
- Evidence from Norway indicates that localized wealth-tax reductions can attract wealthy taxpayers: a municipal reform was associated with a 4.8% increase in the weighted number of wealth-tax payers and a larger increase in reported taxable wealth. The study nevertheless found no evidence of a large national exodus.[2]
- Historical reporting on France's wealth tax documented departures of wealthy taxpayers, although the scale and tax causality are contested.[3]
Evidence against the claim- The claim is too categorical: available evidence generally finds that tax increases cause some movement, not that billionaires broadly leave the country. The large U.S. study found that embeddedness in communities plays a central role and that tax incentives influence migration only at the margin.[1]
- The Norway evidence directly undercuts a broad national-flight interpretation: researchers found that migration responses were concentrated locally and did not imply a large-scale national exodus.[2]
- Research summarized by Forbes reports near-zero long-run migration elasticities among millionaires after major U.S. tax changes, with revenue from those who stay exceeding revenue lost from those who move; it also reports negligible migration effects in research on Sweden's former wealth tax.[4]
- The frequently cited French figures concern millionaires and taxpayers rather than billionaires, and departures cannot automatically be attributed to wealth taxation alone. That makes them weak evidence for the statement as written.[3]
How sure this lab was82/100 — the lab’s own confidence in the score above, not a second reading of the claim.
SourcesRussell Sage Foundationedu · 88 · Wiley Online Libraryjournal · 86 · Yahoo Financenews · 72 · Forbesnews · 78
xAI · EQUAL WEIGHT · 124.0s
grok-4.6
26%BALONEY
ROUND-1 BREAKDOWN
Evidence offered for the claim- Some high-net-worth individuals and billionaires have relocated internationally after wealth or top-rate tax increases (e.g., several Norwegian cases to Switzerland).
- Peer-reviewed studies of highly mobile high earners (inventors, athletes) find statistically significant location responses to cross-country top tax differentials.
- France's former solidarity wealth tax (ISF) was widely linked by contemporaneous reporting and later policy reviews to emigration of wealthy households, contributing to its reform/repeal.
Evidence against the claim- U.S. administrative-data studies of millionaires find only modest or negligible interstate migration responses to tax differences; family, firm, and social ties dominate.
- Very few U.S. billionaires expatriate or renounce citizenship; official expatriation lists remain small relative to the population of the ultra-wealthy.
- Billionaire location is constrained by operating businesses, talent ecosystems, and personal factors; high-tax jurisdictions continue to host large numbers of ultra-wealthy residents.
- Exit taxes and other anti-avoidance rules can substantially blunt pure tax-driven flight.
How sure this lab was68/100 — the lab’s own confidence in the score above, not a second reading of the claim.
SourcesAmerican Economic Reviewjournal · 96 · American Sociological Reviewjournal · 90 · National Bureau of Economic Researchother · 85
Station 2 · The Masters
Primary Master · drawn at random
grok-4.6
35% BALONEY
The statement as written is a blanket causal rule. All five evaluators found a real but narrow mechanism—some highly mobile rich people do relocate after tax changes, especially in small open economies with free movement—while rejecting the implication that taxing billionaires generally drives them out. I weighted peer-reviewed administrative studies (Young et al. on U.S. millionaires; the Kleven et al. JEP review) over news anecdotes from Norway and France, which document some departures at very small rates. U.S. citizenship-based taxation and the exit tax further undercut the claim where it is most often used. That is omitted context and a misleading implication, not a fully fabricated mechanism, so the score sits in Stinky Baloney rather than Rotting or Super Fresh.
All five agreed the claim is too categorical, that some tax-motivated moves occur at the margin, and that family, firms and social ties sharply limit flight. All leaned on Young et al. (American Sociological Review) for low U.S. millionaire migration. They disagreed on weight: Report 3 (26) credited real HNWI mobility more; Report 4 (45) treated U.S. worldwide taxation and exit taxes as nearly decisive and called tax flight largely a myth; Reports 1, 2 and 5 clustered around 32–36. France and Norway were the main split—accepted as evidence of some departures, disputed as evidence of an exodus.
Blind Validation Master · never saw the Primary’s work
gemini-3.1-pro-preview
35% BALONEY
The claim relies on a kernel of truth but exaggerates it into a misleading general rule. Historical and recent examples from Norway, France, and within the EU demonstrate that some high-net-worth individuals do relocate in response to tax increases. However, multiple peer-reviewed studies using extensive administrative data reveal that the vast majority of the ultra-wealthy do not move. Billionaires are typically 'embedded' in their home countries through deep social, family, and business ties, making their overall migration rates remarkably low (often lower than the general population). Furthermore, the claim ignores significant structural barriers in jurisdictions like the United States, which employs citizenship-based taxation and imposes punitive 'exit taxes' on unrealized capital gains for those who renounce citizenship. Because the claim omits these critical facts and implies that an exodus is an inevitable consequence of taxing the ultra-rich, it falls squarely into the 'Stinky Baloney' category.
AGREEMENT TEST PASSED — BOTH MASTERS SCORED 35% · BLIND VALIDATION CONFIRMED THIS SCORE · NO RE-EVALUATION REQUIRED
How the number was reached · scoring model v2 · how our models work
- Median of 5 counted lab scores: 36, 35, 45, 32, 26 → 35.
The Evidence
Evidence offered for the claim
- Norway saw wealthy departures after a tax rise After a 2022 wealth-tax increase, reporting counted a record number of super-rich Norwegians relocating, many to Switzerland, including billionaire Kjell Inge Røkke—more in one year than in the previous 13 combined.
- France's wealth tax drove the rich out of the country DEBUNKED — France's ISF was linked to some 'exil fiscal', but official estimates put annual departures at roughly 500–900 of about 350,000 filers (well under 0.5%), the figures concern millionaires more than billionaires, and tax causality is contested.
- Highly mobile top earners respond to tax differentials Kleven, Landais, Saez and Schultz found Denmark's preferential scheme for foreign high earners roughly doubled inflows. Akcigit, Baslandze and Stantcheva found top inventors' international location responds to top tax rates, especially among the foreign-born.
- Anecdotes and tax-residency regimes attract some movers Eduardo Saverin renounced U.S. citizenship before Facebook's IPO. Switzerland, Italy, Greece, Portugal and the UAE have marketed tax residency to the ultra-wealthy, and Spain's Madrid wealth-tax rebate produced documented within-country relocation.
- OECD flags mobility as a wealth-tax concern The OECD's review of net wealth taxes lists mobility, avoidance, valuation problems and administration among reasons countries worry about or have repealed wealth taxes.
Evidence against the claim
- U.S. millionaire tax flight is small Young, Varner, Lurie and Prisinzano, using tens of millions of tax records, found millionaire interstate migration lower than the general population (about 2.4% vs 2.9% annually), with only a tiny share of moves attributable to tax differentials.
- The rich are socially and economically embedded Family, firms, professional networks and cultural ties substantially limit mobility; research finds tax incentives influence migration only at the margin, not as a general exodus.
- U.S. billionaires cannot escape tax by moving The United States taxes citizens on worldwide income regardless of residence. Renouncing citizenship triggers an exit tax under IRC §877A on unrealized gains, and official expatriation lists remain small relative to the ultra-wealthy population.
- Headline cases are tiny in proportion Norway's 2022 departures were dozens of people among tens of thousands of wealth-tax payers, with no evidence of a large national exodus. French ISF departures were well under 0.5% of filers; revenue problems owed more to exemptions and avoidance than emigration.
- Revenue from stayers exceeds losses from leavers Forbes-summarized U.S. work, Advani, Burgherr and Summers on the UK non-dom reform, and the EU Tax Observatory find that taxes on the very wealthy still raise substantial net revenue because so few leave.
- Large responses are confined to narrow, footloose groups The Journal of Economic Perspectives review finds migration elasticities can be large for foreign professionals, athletes or retirees in low-barrier settings, but much smaller for native top earners as a class.
Sources · Reliability · Why Accepted or Discounted
| Source | Type | Reliability | Ruling |
|---|
| Russell Sage Foundation | edu | 88 | ACCEPTED — Outlet for the core administrative-data research on millionaire migration and embeddedness. |
| Wiley Online Libraryunverified | journal | 86 | ACCEPTED — Peer-reviewed Norway municipal wealth-tax study; supports local attraction without a national exodus. |
| Yahoo Finance | news | 72 | DISCOUNTED — Secondary news recap of contested France/California anecdotes, not primary data. |
| Forbesunverified | news | 78 | ACCEPTED — Commentary, but it reports near-zero long-run millionaire elasticities consistent with the academic literature. |
| The Guardian | news | 82 | ACCEPTED — Credible reporting of Norwegian departures; the headline overstates scale, which the panel already flags. |
| OECDunverified | gov | 92 | ACCEPTED — Authoritative review of net wealth taxes and the mobility concern. |
| Journal of Economic Perspectives | journal | 95 | ACCEPTED — Standard review of taxation and migration; distinguishes large responses for narrow groups from small ones for native top earners. |
| Quarterly Journal of Economicsunverified | journal | 95 | ACCEPTED — Kleven, Landais, Saez and Schultz Denmark study; high-quality evidence of tax-motivated migration among foreign high earners. |
| Quarterly Journal of Economicsunverified | journal | 95 | ACCEPTED — Same Kleven et al. Denmark paper as cited with an alternate URL fragment. |
| American Sociological Reviewunverified | journal | 94 | ACCEPTED — Young, Varner, Lurie and Prisinzano; the central administrative-data finding that millionaire migration is low and only marginally tax-driven. |
| American Economic Review | journal | 96 | ACCEPTED — Peer-reviewed evidence that some highly mobile high earners respond to cross-country tax differentials. |
| National Bureau of Economic Research | other | 85 | ACCEPTED — Working paper cited for modest U.S. migration responses; not a substitute for the published ASR results. |
| Internal Revenue Service | gov | 100 | ACCEPTED — Primary legal source for the U.S. exit tax under IRC §877A. |
| NPRunverified | news | 90 | ACCEPTED — High-quality news explainer of European wealth-tax repeals; used as context, not as proof of mass flight. |
| Center on Budget and Policy Prioritiesunverified | other | 85 | DISCOUNTED — Advocacy brief restating Young et al.; the underlying journal article is the evidence. |
| Center on Budget and Policy Prioritiesunverified | other | 68 | DISCOUNTED — Same think-tank brief via an alternate path; secondary to the peer-reviewed study. |
| American Economic Review | journal | 94 | ACCEPTED — Akcigit, Baslandze and Stantcheva on inventor mobility; solid evidence for a narrow, highly mobile group. |
| American Economic Review | journal | 94 | ACCEPTED — Moretti and Wilson on star scientists and state taxes; shows mobility where moving costs are low, not a national billionaire exodus. |
| EU Tax Observatory | other | 80 | ACCEPTED — Independent tax-research body; supports the finding that revenue from taxing the very wealthy exceeds losses from the few who leave. |
Every link was opened when this claim was inspected. A dead link was discarded before publication; “unverified” means the site refused our automated check and the link is the one the panel cited. A source without a URL was never kept.
Serve It Fresh
Ready to Serve19 servings
Serve it the way you want it
The Verdict
“Taxing billionaires drives them out of the country.”35% Stinky Baloney — Seriously OffVerified blind by 5 frontier AIs · Baloney Inspection Report: baloney.ai/baloney/taxing-billionaires-drives-them-out-of-the-country